All Categories
Featured
Mastering Financial Literacy for Adults in 2026
Table of Contents
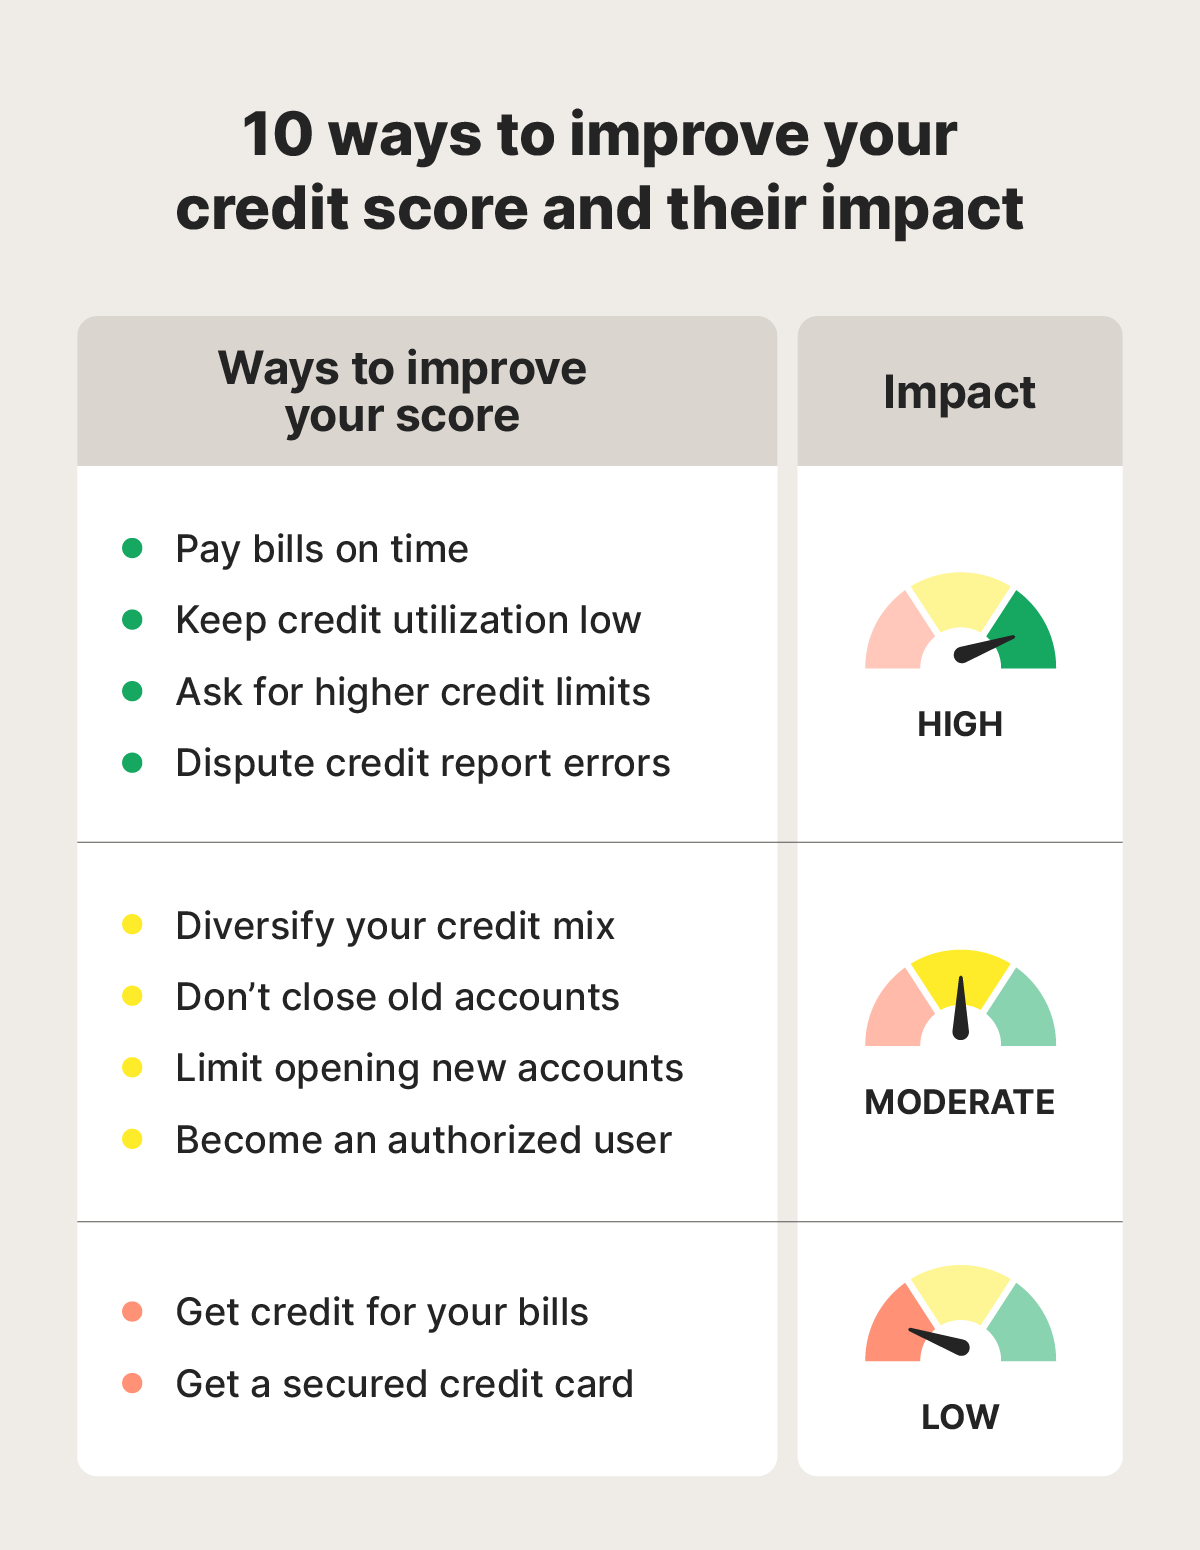
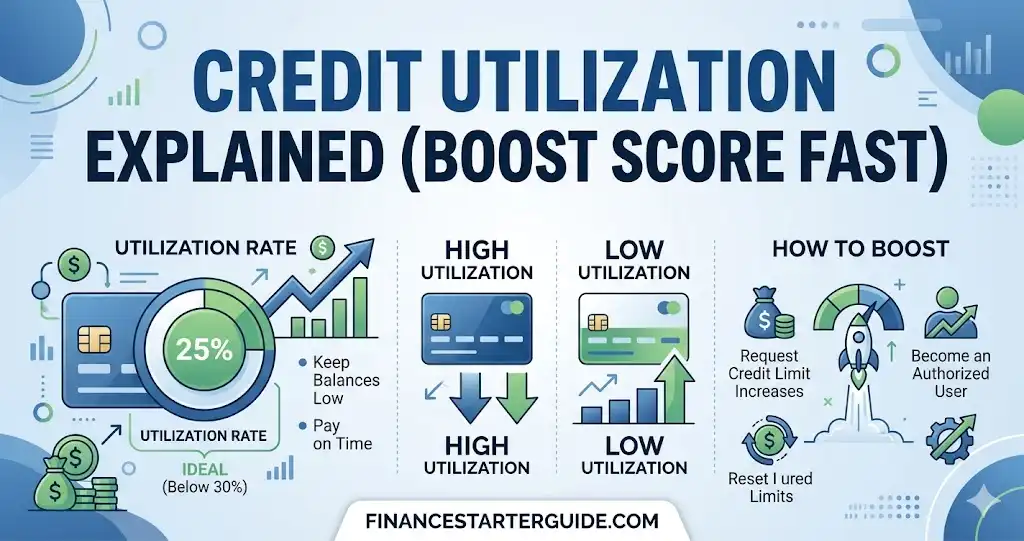
Results differ depending upon the number of missed out on payments you have and how far unpaid they are. Missed payments remain on your report for 7 years, however their impact fades over time. Your credit utilization ratio, the quantity of credit you're utilizing versus what's readily available, accounts for 30% of your FICO Score and 20% of your VantageScore.
Within a month of your new utilization ratio being reported to the credit bureaus. That card's credit limit and history get factored into your own rating.
As a licensed user, the main cardholder's habits impacts your credit too. Once it's authorized and reported, it can decrease your credit usage and boost your credit rating.
The key is to not contribute to those balances. If your income has actually increased or you have a strong payment history, you're a great prospect for an increase. Ask your issuer whether a tough questions is required first, as that can temporarily reduce your score. Fast once the higher limitation is reported to the bureaus, your usage ratio drops and your score must follow.
You can also challenge the info if it's incorrect or too old to be noted. FICO 8, the most frequently utilized version, counts paid and unsettled collections on debts of $100 or more. Newer designs, FICO 9 and 10, disregard paid collections totally and deal with overdue medical collections less seriously.
How Expert Financial Guidance Improves Your ScoreQuick Tips to Rebuild a Credit Profile Today
Get individualized debt relief solutions that may reduce what you owe and assist you regain monetary stability. These cards are backed by a cash deposit (generally paid upfront), which acts as your credit line. They work like a regular charge card and report your payment history to the bureaus the exact same way, so consistent on-time payments construct your score gradually.
If you have a thin credit profile, tools like Experian Increase can help you build it out by, such as rent, energies and streaming services. Not all scoring designs aspect in this information, however where it's thought about, a consistent record of on-time payments can meaningfully improve your score. As quickly as the information is reported to the bureaus.
Closing old accounts shortens your credit history and can increase your credit utilization. Combined, this might lower your credit rating.
Closing your earliest account minimizes your average account age, increases credit utilization and can reduce your rating when reported to the credit bureaus. It represents 10% of your FICO Score and is not factored into VantageScore at all. If you just have credit cards, taking out a small individual loan could enhance your score.
Be cautious of taking out new credit simply for the sake of improving your credit. Focus on naturally blending up your credit over time.
Learning Key Financial Literacy Skills for Today's Adults
The time it takes will depend upon the private factors impacting it and the steps you take to change them. A credit limit increase or ending up being a licensed user can show outcomes within a billing cycle. Recuperating from missed payments or collections can take months. Fortunately: unfavorable products fade in impact over time and fall off your report completely within 7 to ten years.

Do not close old accounts, even ones you seldom use. Keep your very first credit card active by putting a little repeating charge on it, like a streaming membership, and pay it off each month. Closing old accounts reduces your credit history and can increase your credit utilization. Combined, this could decrease your credit score.
Closing your earliest account minimizes your average account age, increases credit usage and can reduce your rating when reported to the credit bureaus. It represents 10% of your FICO Rating and is not factored into VantageScore at all. If you just have credit cards, taking out a little personal loan could increase your score.
Be cautious of taking out new credit simply for the sake of improving your credit. Focus on naturally blending up your credit over time.
The time it takes will depend on the individual aspects affecting it and the actions you take to alter them. A line of credit boost or ending up being an authorized user can show results within a billing cycle. Recovering from missed out on payments or collections can take months. The excellent news: negative products fade in impact gradually and fall off your report totally within seven to 10 years.
How Professional Financial Guidance Improves Your Score
Do not close old accounts, even ones you seldom use. For example, keep your first charge card active by putting a little recurring charge on it, like a streaming membership, and pay it off every month. Closing old accounts reduces your credit history and can increase your credit usage. Integrated, this could lower your credit rating.
Closing your oldest account minimizes your typical account age, increases credit utilization and can lower your rating when reported to the credit bureaus. It accounts for 10% of your FICO Rating and is not factored into VantageScore at all. If you just have credit cards, taking out a little individual loan could increase your score.
Be wary of securing new credit simply for the sake of improving your credit, nevertheless. Focus on naturally blending your credit gradually. Quick once the new account is reported to the bureaus, you might see a change within a billing cycle. See LendingTree's complete guide on how your credit report is calculated.
The time it takes will depend on the individual elements affecting it and the steps you take to change them. A credit line boost or becoming an authorized user can show outcomes within a billing cycle.

Latest Posts
Accessing Free Credit Counseling Near Me in 2026
Smart Credit Building Strategies for Year 2026
Effective Strategies to Raise Credit Scores